Manifesto · Single-Family Mandate
Every month a family asks us to manage their wealth. Every month we decline — politely, and on principle. Neyius exists to build businesses, not to gather assets. We are a single-family operating office: one family’s capital, fully committed to acquiring, operating and restoring real enterprises. That refusal is our strategy.
- 100% of advisory bandwidth dedicated to the internal portfolio; zero external wealth-client friction.
- Single-family structure enables 5–10 year holds, through-cycle CapEx and 60% board control — impossible under redemption risk.
- Outsiders engage as founders, co-investors, customers or consulting clients — never as AUM.
- Start here, then read: Patient Capital · Active Governance · Business Ownership.
1. The AUM trap we refused
The multi-family model is seductive: gather assets, clip fees, publish CIO letters. But it carries hidden taxes. Clients redeem at the worst moment, forcing sales. Committees demand quarterly narratives, forcing short-termism. Conflicts multiply: whose family gets the best co-invest? Family Wealth Report and Institutional Investor regularly document the pressure — scale or die, gather or fade.
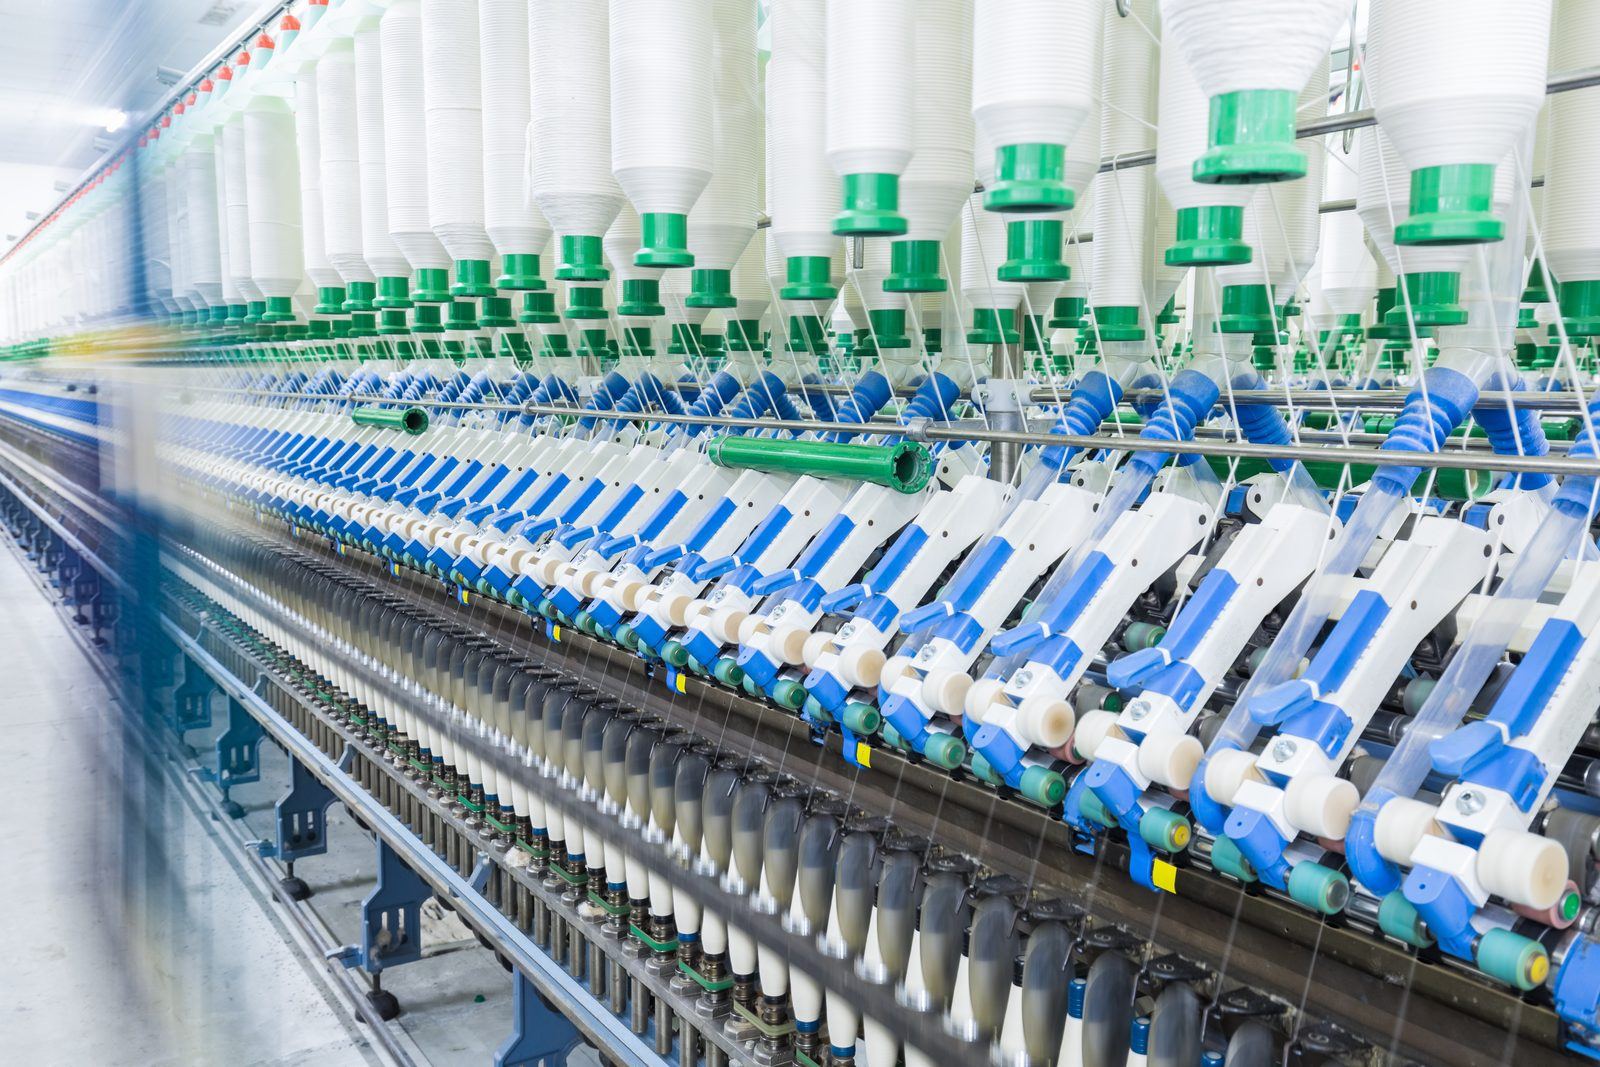
We chose the opposite scarcity: one balance sheet, infinite attention. With no outside redemptions, we can inject equity in a downturn (zero bankruptcies in 12 years), protect CapEx when earnings dip, and hold a textile mill through an 18-month certification or a castle through a four-year restoration. Fee income would have been easier. Ownership is more valuable.
2. What a single-family mandate actually allows
Risk tolerance with a wrench. Because we operate the asset, risk is not a volatility number — it is a repair schedule. Our 18% average IRR across emerging holdings (see Patient Capital) comes from margin expansion (8%→22% EBITDA in one turnaround, see Case Study), not leverage gymnastics.
Governance depth. Neyius executives hold ~60% of board seats and cut decision latency 45%. No outside client committee would approve that intrusiveness; as owners, we insist on it (see Why Governance Matters).
Reinvestment without apology. Early cash flows fund water loops, dispatch software and apprenticeships — the unglamorous compounding behind a 15% B2B premium (see ROI of Purpose) and 250,000 newly powered households (see Energy Transition).
“We do not want a thousand clients. We want a dozen businesses we would be proud to own for fifty years — and the freedom to act like it.” — Courtney Jordan
3. Exhibit: single operating vs. multi-family advising
| Dimension | Neyius single-family (index) |
|---|---|
| Bandwidth to owned ops | 100 |
| Typical multi-family to any one holding | 22 |
| Board control (Neyius avg) | 60 |
| Hold period (years, Neyius avg) | 72 |
Hold-period indexed (months × factor) for charting; see text for actuals (5+ yr avg). Table canonical.
4. How to work with us — without being a wealth client
Founders: sell control or take a 20–40% partner who does not need to flip in three years (see Founder’s Guide and Minority Stakes). 90% founder retention post-acquisition is our reference, not our slogan. Enterprises: buy from Meridian East, Rimvo, Nervyra and Textiles — audited, warrantied, on time. Peers & DFIs: co-invest via catalytic structures ($1:$8 leverage, see Catalytic Capital). Operators: hire Neyius Advisors for 6-month transformations averaging $5M+ in identified savings.
5. Answering the skeptics
“Isn’t concentration risky?” Concentration without control is. With embedded operators, local balance sheets and 10 hubs across 5 regions (see 10-City Strategy), concentration is diligence. “How do you benchmark without peers?” Against our own P&Ls: availability, yield, latency, retention — plus institutional standards (B Lab 115, 99.99% SLAs). “Will you ever raise a fund?” No. The mandate is the moat. While others manage wealth, we build the assets wealth is made of.
If you need a wealth manager, we will gladly introduce excellent multi-family firms. If you need an owner who will restore your factory, harden your grid and still answer the phone in year seven — talk to Neyius.
Handling the three honest objections
Concentration risk. A single family balance sheet backing grids, mills and castles is concentrated by definition. We mitigate with local-currency debt, through-cycle CapEx shields, and weekly governance that catches drift early — the same controls behind zero bankruptcies in twelve years and the 8%→22% margin turnaround in our case study. Concentration with operators is diligence; diversification without them is diffusion.
Succession. Single-family does not mean single-person. Charters, independent boards, and next-gen operator rotations (see Generational Wealth, Built) institutionalize judgment beyond any founder. Our annual letter — revenues +22%, 14% EBITDA in the Q4 2025 edition — is written to be readable by a grandchild inheriting the workshop, not just a CIO defending a quarter.
Opportunity cost. Could fee income fund more building? Perhaps, but it would cost the very focus that makes building work. One hundred percent of advisory bandwidth to owned operations buys 45% faster decisions, 60% board control, and the trust that unlocks proprietary transitions 12–18 months before bankers. That compounding — documented across Patient Capital and Active Governance — exceeds any fee margin we forgo.
FAQ
Are you a private-equity fund?
No. No fund, no carry clock, no exits owed to LPs. Hold periods average 5+ years; many assets are indefinite holds (heritage estates: 500-year lens).
Do you co-invest?
Selectively, on significant stakes alongside founders and DFIs — governed by operating agreements, not fund docs. See Minority Stakes.
Where is this documented?
Sources: Neyius operating reviews; Family Wealth Report industry benchmarks. External links for context only.