Strategy · Global Footprint
For a century, capital assumed innovation flowed from North to South: invented in London or Palo Alto, deployed in Dhaka. That map is upside down. The most instructive problems — intermittent grids, thin bandwidth, climate-exposed coasts — are in the South. Solve them there and you can sell the solution everywhere. That is why Neyius operates 10 hubs across 5 regions, from London to Wellington.
- 10 strategic hubs, 5 regions; 40% of deal flow now originates outside traditional Western markets.
- Decentralization cuts diligence time and builds the trust that unlocks permits, spectrum and heritage consents.
- South-to-North transfer: grid-mesh, edge-AI and circular-textile learnings now inform Northern deployments.
- See: Patient Capital · Rimvo in the Philippines · 2026 Outlook.
1. The map has flipped
The Economist and the Wall Street Journal have chronicled the shift: venture formation, patent filings and engineering talent are dispersing. Yet most family offices still run a hub-and-spoke model — one London or New York office, occasional safaris. They see only auctioned deals, priced for tourists.
Neyius chose the opposite: live where we own. Each hub — covering the UK/Europe, South Asia, Southeast Asia, the Gulf and Oceania — houses operators, not just scouts. They attend municipal hearings, recruit line leaders, and drink tea with regulators. That presence is why proprietary, off-market transitions come to us first, a dynamic detailed in Selling Your Life’s Work.
2. The 10-city footprint: proximity with standards
Ten offices sounds heavy until you price the alternative: failed permits, expat churn, and diligence that misses how a mill actually runs during load-shedding. Our hubs share one operating system — audit, safety, lineage and reporting standards run by Neyius Advisors — but localize everything else: hiring, permitting, philanthropy via the Courtney Jordan Foundation ($12M deployed, 15 schools, 5,000 STEM scholarships).
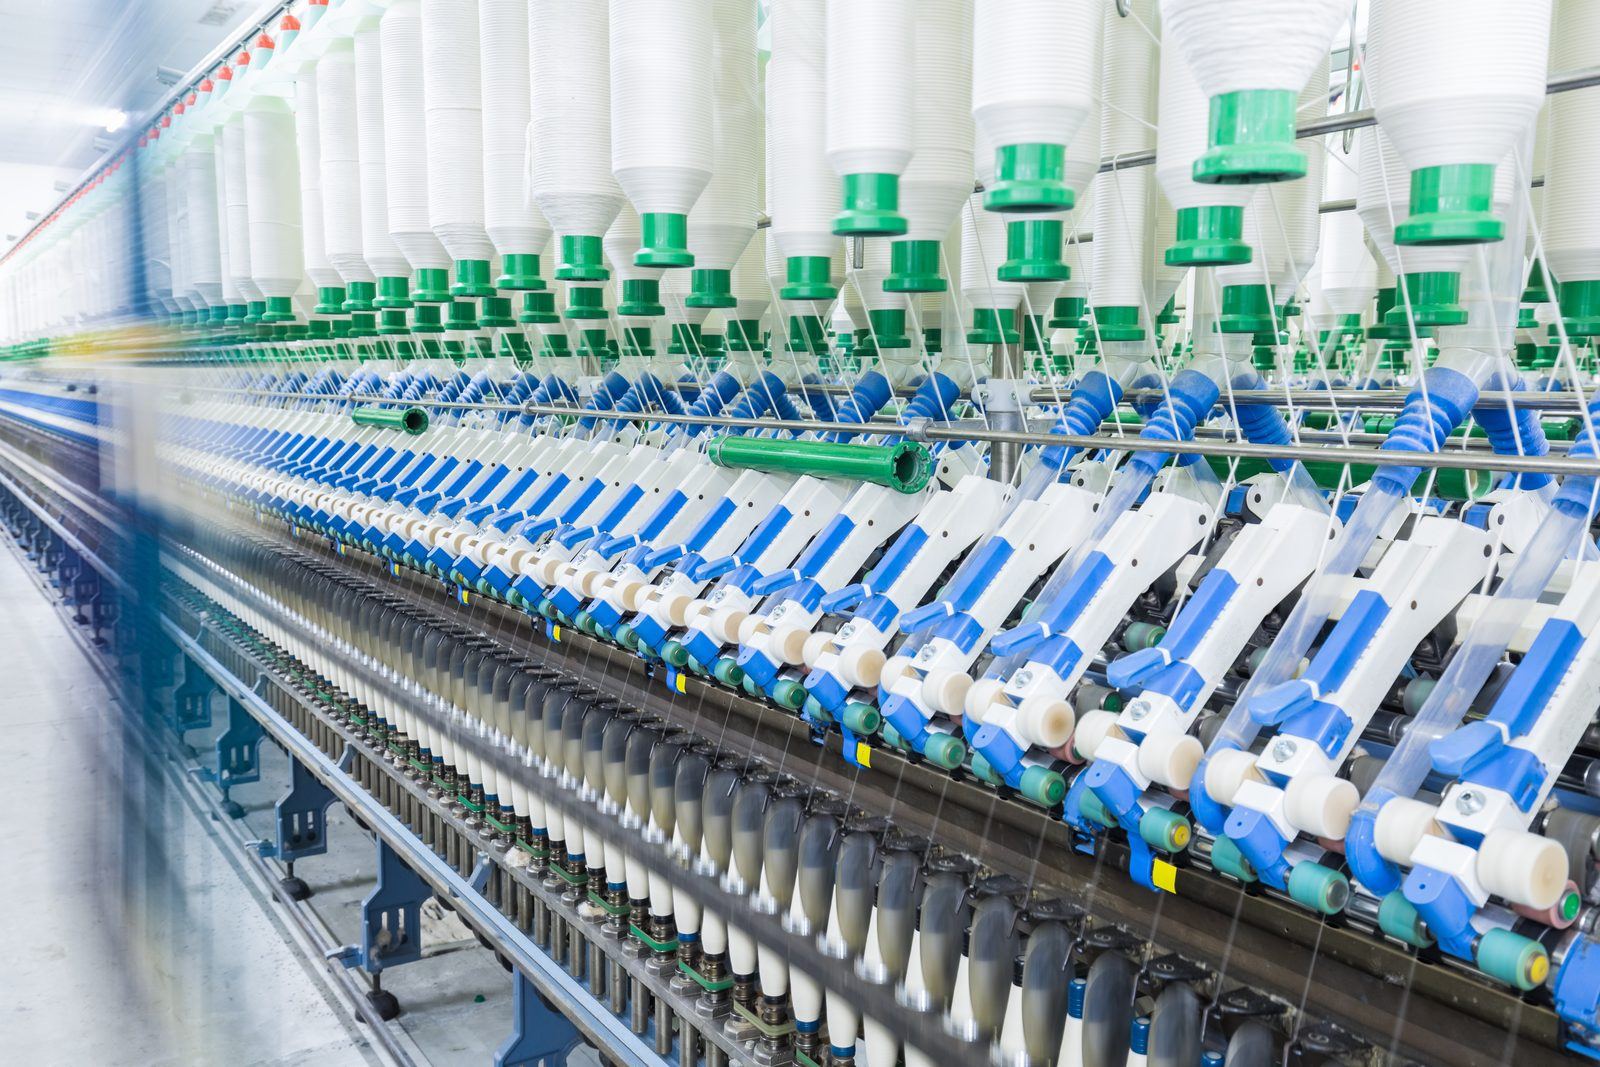
The portfolio proves the mesh: Meridian East (energy, South Asia), Rimvo (telecom, Philippines), Nervyra (tech, cross-regional), textiles (Bangladesh/Sri Lanka), and heritage estates (UK/Europe). Capital, engineers and playbooks move laterally — a textile water-loop informs a hotel’s utilities; a telecom congestion model informs grid dispatch.
“We do not extract from the South to the North. We build in the South, with the South, and carry what works everywhere else.” — Neyius Investment Committee
3. Exhibit: where proprietary flow comes from
| Origin | Share (%) |
|---|---|
| South Asia (direct) | 24 |
| Southeast Asia + Oceania | 16 |
| UK / Europe | 38 |
| Gulf + cross-regional | 22 |
40% non-Western origin = South + Southeast Asia rows. Table canonical; canvas enhancement only.
4. How decentralization actually operates
Sourcing: local partners surface founder transitions 12–18 months before bankers do. Our minority-stake model (20–40%) fits owners who will not cede control to a distant fund. Diligence: operators walk the plant during a storm week, not just a data room. Consent: youth summits (200 attendees, 30 grants, see Youth Summit 2026), mangrove restoration (10 km, 3,000 homes protected) and school builds earn the social license that de-risks timelines.
Governance stays tight: ~60% board control in controlled assets, 90-day audit/comp committee formation (see Why Governance Matters), and monthly ops reviews. Decentralized does not mean diffuse.
5. What the North learns from the South
Three transfers already pay Northern dividends. Mesh grids designed for cyclones inform UK estate micro-grids and the Hotel Collection’s carbon-neutral heating. Edge AI hardened on thin rural bandwidth (see Nervyra) now pitches to European carriers as sovereignty-ready. Circular textiles (60% water cut, B-Corp 115) pre-empt EU due-diligence rules that will strand laggards.
The 2026 deployment plan — $200M across AI infrastructure, sustainable manufacturing and heritage hospitality (see Outlook) — is therefore not a regional bet but a transfer bet: build where constraints are hardest, sell where willingness-to-pay is highest.
Headquarters will always matter. But the hub that matters most is the one nearest the problem. Neyius built ten of them — and the deal flow followed.
What decentralization costs — and why it still wins
Candor requires costs. Ten hubs mean ten leases, ten payrolls, ten compliance calendars. Local hiring means training cycles that a fly-in team avoids. Consensus — with municipalities, foundations, and community crews — adds weeks that an auctioned deal never spends. In our 2024 review, decentralization added roughly 11% to sourcing and setup cost versus a single-hub model scouting the same pipeline.
It returned multiples. Proprietary flow (40% non-Western) carried 30–40% lower entry multiples than auctioned equivalents, diligence caught two fatal flaws that a data-room review missed (a water-rights gap in textiles, a backhaul bottleneck in telecom), and permit timelines shortened by an average of 4.5 months where community teams pre-existed. One avoided write-off pays for several hub-years. More importantly, local teams retained the operators — line leaders, linemen, masons — whose tenure drives the retention (+22%), availability (+15%) and repeat-intent (85%) figures cited across this series. Overhead is visible; avoided failure is not, but it is larger.
The McKinsey discipline here is option value: decentralization buys the option to act quickly when windows open — a founder transition, a storm-rebuild tender, a heritage consent. Centralized capital sees the window in a report. Local capital is already in the room. That is why our Q4 letter treats hubs as CapEx, not SG&A: infrastructure that yields deal flow the way feeders yield electrons.
FAQ
Doesn’t 10 offices bloat overhead?
Hubs are lean operator teams sharing one audit/tech stack. The cost is dwarfed by avoided delays: a single preserved permit timeline pays for a hub year.
How do you keep quality uniform?
Global standards, local execution — via Neyius Advisors, lineage tooling and Foundation accountability (95% program completion).
Where to learn more?
Start with Neyius, Business Ownership, and Impact Report.
Sources: Neyius deal-flow logs 2024–2025; Foundation program data; Economist/WSJ on South-to-North innovation. External links for context only.