Annual Forecast · 2026 · Investment Committee
Every January we publish where patience pays next. For 2026, Neyius targets $200M in new deployments across AI infrastructure, sustainable manufacturing, and heritage hospitality — three sectors where the myopia tax is highest and the patient premium therefore largest.
- $200M targeted: sovereign AI + edge; certified manufacturing; 2026 hotel openings.
- 2025 base: +22% revenue, 14% EBITDA, 18% avg IRR, zero bankruptcies (see Q4 letter).
- Thesis in one line: buy time where others must sell it.
- Act: Sell us your company · Co-invest / buy.
1. AI infrastructure: sovereign, small, and boring (on purpose)
Nervyra’s 2025 proof — 3 patents, −40% latency, $12M ARR carrier deal at 99.99% — funds the 2026 build: sovereign single-tenant packs for telecom/energy regulators, distilled 7–13B edge runtimes for thin bandwidth, and unglamorous integrations (ticketing, SCADA, billing). The 30-person tuck-in staffs it. Bloomberg and FT readers know the hype cycle; we underwrite the hardening cycle — multi-year, auditable, and priced on uptime, not demos (see Nervyra thesis).
2. Sustainable manufacturing: certify remaining lines, publish intensity
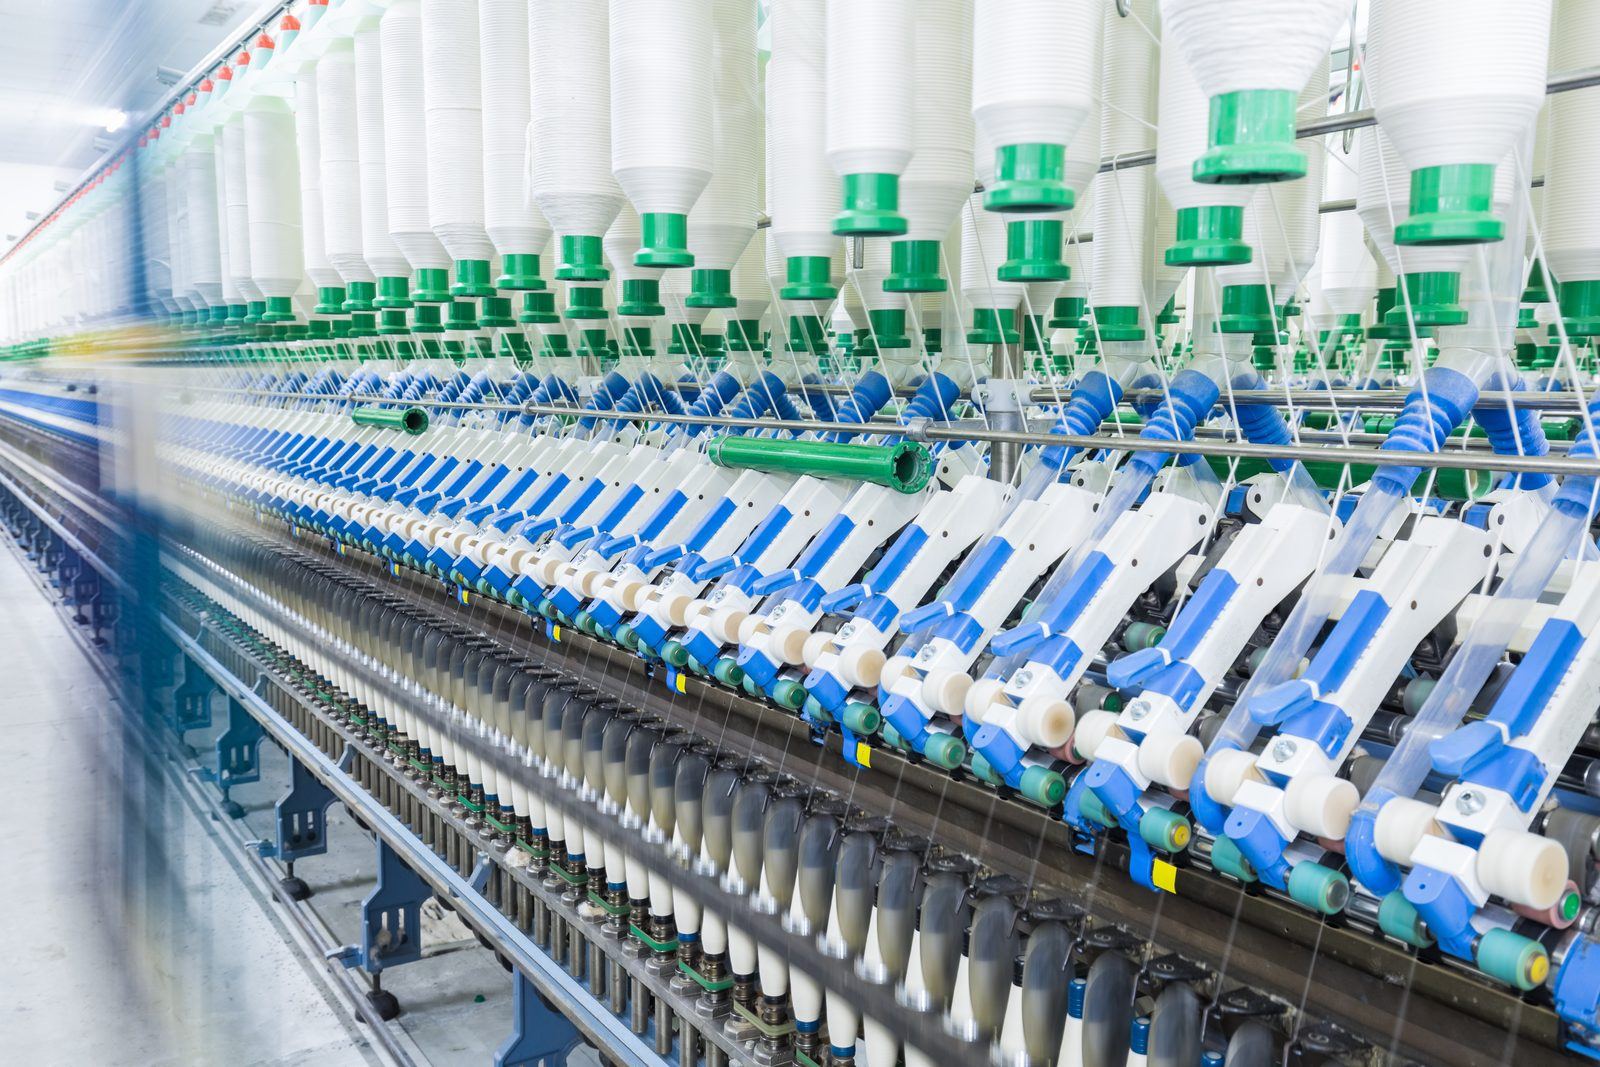
Textiles proved the loop: B-Corp 115, water −60%, 2 mills 100% renewable, +22% retention, +15% premium (see B-Corp and Purpose ROI). 2026 extends certification, publishes per-unit water/energy, and templates workforce standards (65% female, equal pay, $2M care/leadership; see Women) to new platforms. EU due-diligence rules will strand laggards; certified supply will price like insurance — because it is.
3. Heritage hospitality: Fall 2026 openings, then centuries of harvest
The 45-suite flagship (12k spa, Michelin partner, 1:3 staffing, max 20 per experience) opens phased from Fall 2026, underwriting the $15M → 30% IRR → 500-year model and the +40% ADR / 85% repeat thesis. Experiences attach monetizes memory; regional uplift (£500M) compounds consent. While others build to flip, we restore to keep — duration as luxury.
“We do not predict 2026. We prepare for 2036 — and let 2026 pay us for the discipline.” — Courtney Jordan
4. Exhibit: indicative $200M deployment
| Sector | $M |
|---|---|
| AI infrastructure (sovereign + edge) | 70 |
| Sustainable manufacturing | 65 |
| Heritage hospitality | 65 |
Targets, not commitments. Table canonical; canvas enhancement only.
5. Risks we respect (counsel insists, experience agrees)
Permitting (castles, feeders, towers), weather (monsoons, coasts), supply chains (storage, edge silicon), rates/FX (local-currency discipline), and execution (integration of 30-person teams). Mitigants are structural: no redemptions, through-cycle CapEx, local balance sheets, weekly governance (see Active Governance), and the right to walk from misaligned deals — as in two 2025 passes. Philanthropy braids alongside: $12M, 95% completion, $1:$8 leverage (see Catalytic Capital).
Founders in these sectors: sell us control or partner minority. Enterprises: buy our electrons, connectivity, textiles and nights. Peers/DFIs: co-invest catalytic tranches. While others manage wealth, we will keep building what wealth is made of.
How to act: founders, buyers, co-investors
Founders: if you operate in AI infra, sustainable manufacturing or heritage assets, bring 3-year ops logs and a willingness to govern weekly — via control sale or 20–40% partnership. Proprietary, off-market transitions close fastest; bankers are optional. Enterprises: buy availability — electrons (150 MW, +15% stability), connectivity (500 towers, 1.2M), certified textiles (B-Corp 115), governed AI (−40% latency, 99.99% uptime). DFIs/peers: catalytic tranches ($1:$8) via blended structures and data room. While FT/Bloomberg debate 2026, we will be commissioning it — feeder, loom and stone at a time.
What could make us wrong — and what we will do
Three scenarios change the plan: permitting freezes (heritage consents, grid interconnection), input shocks (storage, edge silicon, FX), and integration misses (tuck-in velocity, carrier acceptance). Responses are pre-wired: shift CapEx across the three sectors rather than forcing timelines, localize supply where quality allows (racking, spares, craft), and publish misses with fixes in the February 2027 letter — the standard set in our Q4 2025 edition. Bloomberg/FT forecasts often assume mean reversion; operators assume weather. We underwrite the decade, stage the year, and report the quarter honestly — patient capital’s only edge, compounded across 10 hubs, $12M in giving, and assets built to outlive us.
FAQ + invitation
Is $200M committed?
Targeted, staged on diligence and governance fit. Reported in the February 2027 letter with misses in ink.
How to track progress?
Follow the cluster: Patient Capital → Q4 letter → vertical releases → this outlook, annually.
Who to contact?
Sources: Investment Committee plan; portfolio management figures (unaudited). External links for context only.