Case Study · Operational Value Creation · Neyius Advisors
The teaser called it “a light-manufacturing asset with headwinds.” Translation: missed shipments, tired machines, and an 8% EBITDA margin sliding toward zero. Thirty-six months later the same plant led its niche on quality, posted 22% EBITDA margins, and carried a $45M enterprise value on $12M of equity — a 3× MOIC. No leverage magic. Just operations.
- Entry: $12M equity; exit valuation: $45M EV; 3× MOIC; EBITDA 8%→22% in 36 months.
- Method: embedded Neyius Advisors team, 90-day governance reset, protected CapEx, repricing on reliability.
- Decision latency −45%; retention and OTIF inflected within two quarters.
- Methodology deep-dives: Active Governance · Post-Founder Boards.
1. Day zero: what $12M actually bought
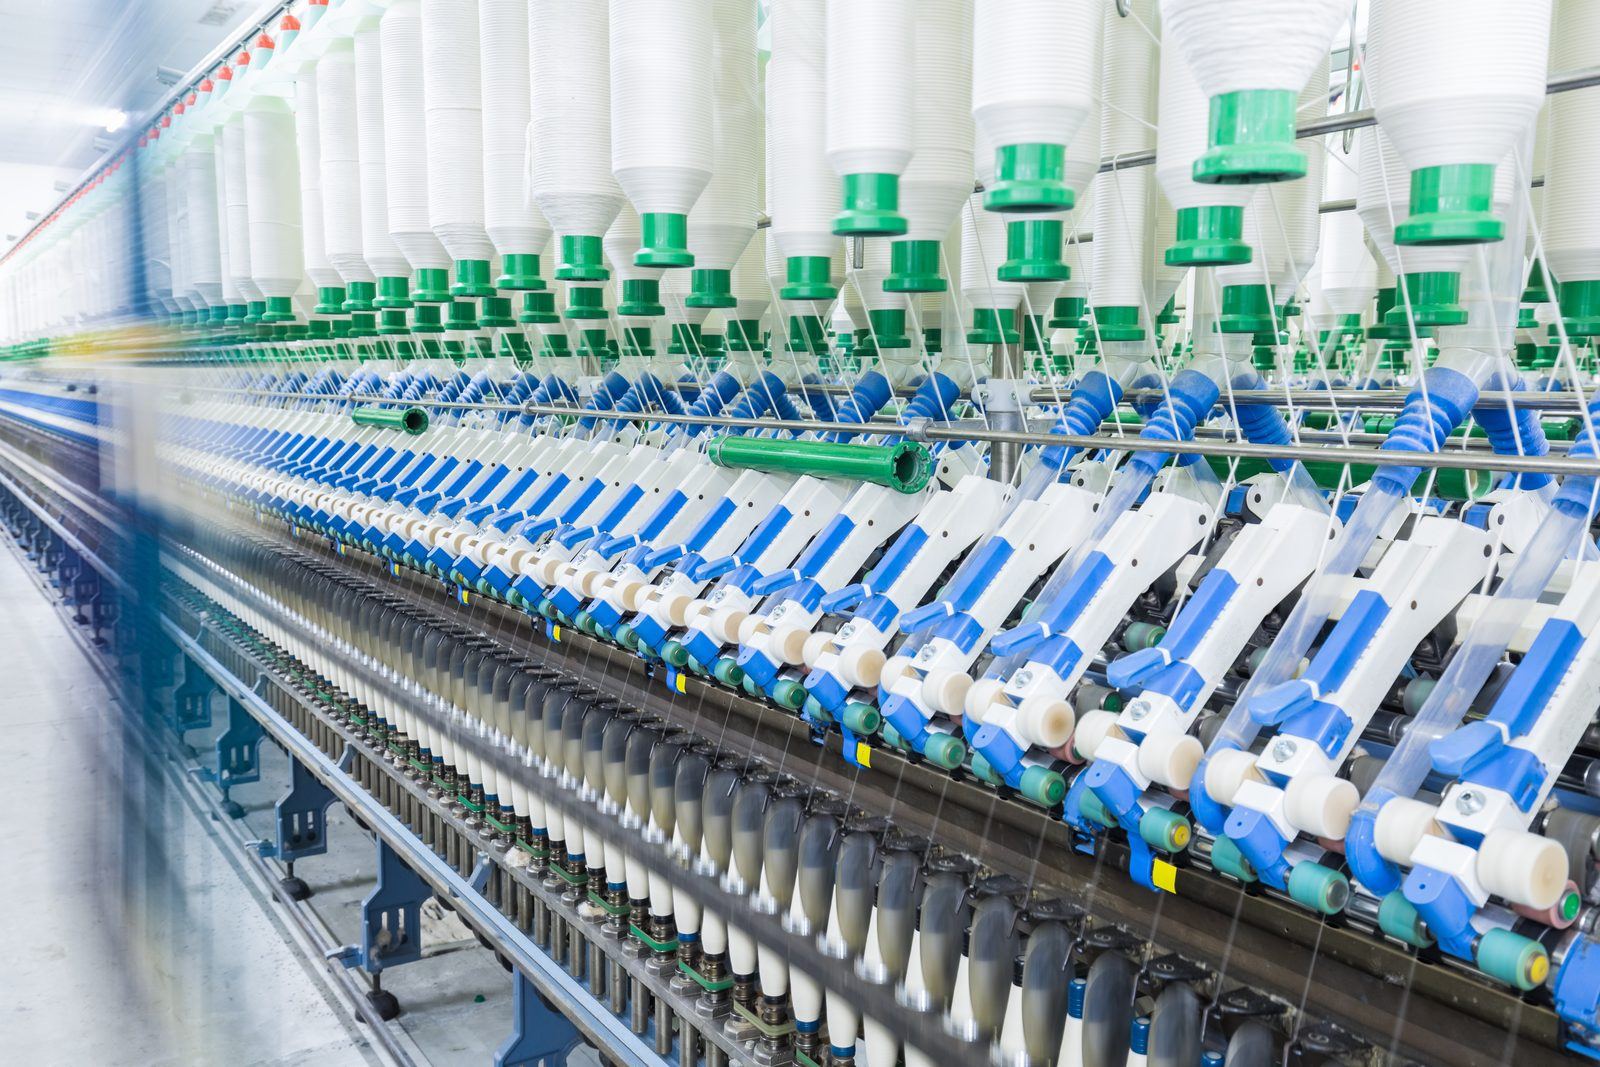
Revenue was flat, but mix was deteriorating: low-margin spot orders filled the gaps left by lapsed framework contracts. Maintenance had been deferred three cycles; unplanned downtime ran 11%. OTIF (on-time-in-full) languished at 82%, so buyers procured elsewhere. The founder — skilled, exhausted — stayed on (as in 90% of Neyius transitions; see Founder’s Guide) but needed a professional board and a CapEx shield.
We underwrote the deal on operations, not multiple expansion: protected CapEx of ~15% of EV over three years, local-currency working lines, and a Neyius Advisors pod (ops, quality, finance) embedded four days a week. The single-family mandate made the structure possible — no IC demanding a year-one dividend.
2. The 90-day governance reset
Board: three independent seats added, audit and comp committees formed — the same 90-day standard in Why Governance Matters. Cadence: weekly ops reviews (safety, yield, downtime, OTIF), monthly P&L with variance to driver, quarterly strategy. Decision latency fell 45% as approvals moved from quarterly packs to weekly rooms. Cash: 13-week rolling forecast; maintenance CapEx ring-fenced even when EBITDA dipped in month two.
Workforce first: attendance bonuses replaced with skill premiums, childcare pilots and line-leader academies — the retention playbook behind our 22% uplift (see ROI of Purpose). Tenure is quality: first-pass yield responds within one quarter when the same hands run the same machines.
“Private equity asks ‘what multiple?’ Operators ask ‘what downtime?’ Fix the second and the first takes care of itself.” — Neyius Advisors, Engagement Lead
3. Exhibit: the 8% → 22% margin bridge
| Driver | pp contribution |
|---|---|
| Starting margin | 8 |
| Downtime & scrap reduction | 5 |
| Mix shift to frameworks | 4 |
| Energy & procurement | 3 |
| Labor productivity (net of premiums) | 2 |
| Ending margin | 22 |
Anonymized composite; table canonical. See group reconciliation in Q4 2025 letter.
4. Months 4–36: compounding reliability into price
With downtime halved, OTIF climbed from 82% to 97%, unlocking two multi-year frameworks. Certified lines — traceable inputs, audited labor — commanded a 15% premium (see Purpose ROI), shifting mix away from spot. Energy retrofits and pooled procurement added three margin points; skill premiums paid for themselves in rework avoided.
Technology helped where it hardened operations: lightweight lineage for quality claims and dispatch-style scheduling borrowed from Nervyra. Nothing flashy — just fewer surprises. By month 30 the plant audited like a textbook and priced like one.
5. Five lessons for any distressed operator
Protect CapEx first. The cheapest turnaround is the maintenance you do not defer. Govern weekly. Boards that meet quarterly govern quarterly. Price reliability, then deliver it. Premiums fund the CapEx that earns them. Promote from the floor. Tenure compounds faster than consultants. Hold long enough to matter. Thirty-six months is a floor, not a flip — the patient-capital edge.
Considering a transition? Read Selling Your Life’s Work and Minority Stakes. If control must change, change it to an owner who will still be there for the night shift in year three.
Transferable to your plant: a 30-day starter
You do not need Neyius to start. Week one: install the weekly ops deck (safety, yield, downtime, OTIF, cash) and a 13-week rolling forecast — no new software required. Week two: walk every line during the worst shift, log the top ten losses in money terms, and ring-fence maintenance CapEx so month-end cannot raid it. Week three: replace attendance bonuses with skill premiums and publish the academy path; tenure responds within a quarter (see Women in Manufacturing). Week four: take one hero product, instrument water/energy per unit, and quote a certified premium to one trusted buyer — the first step toward the 15% documented in Purpose ROI.
Bring that month of data to any buyer — including us via the Founder’s Guide — and valuation changes. You have shown controllability, the scarcest attribute in mid-market M&A. Whether you sell control or take a 20–40% partner, the plant that governs weekly prices like the plant in this case study, not the teaser that preceded it.
FAQ
Was leverage used?
Modest local working-capital lines only. Value came from margin and mix, not multiple arbitrage — hence resilience through rate shocks.
Did the founder stay?
Yes — consistent with our 90% founder-retention rate. Governance professionalized around the founder; it did not replace domain mastery.
Can Neyius Advisors do this as a service?
Yes: 15 partners, ~6-month engagements, $5M+ average identified savings. See Neyius Advisors.
Sources: Anonymized management accounts; Neyius Advisors engagement logs. External context via PEI. Figures illustrative of method; individual outcomes vary.